Flood Risk Poses New Hurdles as Cities Seek to Legalize Basement Apartments
As cities grapple with affordable housing crises, basement apartments offer a potential solution, yet the growing threat of climate-fueled flooding raises safety concerns. New York's pilot program lags, while Chicago, Boston, and others explore accessory dwelling units with flood-resilient regulations. Innovative insurance and risk tools aim to protect vulnerable residents.
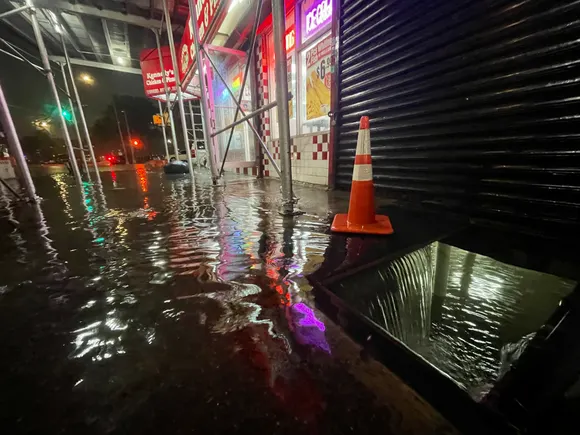
As cities across the United States confront the affordable housing crisis, many are turning to an unconventional answer: the space below ground level. Basement apartments, often illegal and unregulated, present a low-cost way to expand rental stock and provide income for small landlords. However, the strategy now faces a formidable obstacle—the increasing frequency and severity of flooding driven by climate change.
The challenge came into sharp focus in September 2021, when heavy rainfall from the remnants of Hurricane Ida inundated New York City streets and buildings. The storm claimed the lives of 13 New Yorkers, 11 of whom were residing in basement or cellar units. A subsequent city report on extreme weather events concluded that basement units "present an incredibly complex challenge," noting that many were constructed without city oversight and lack essential safety features such as egresses, ventilation, and protected electrical systems.
"Because of those dangers, immediate legalization of every basement unit isn't safe for New Yorkers," the report stated. "Yet because of the need for affordable housing, basement apartments remain an important part of the city's housing stock."
In 2019, the administration of then-Mayor Bill de Blasio initiated a pilot program to convert basements in the East New York neighborhood of Brooklyn into safe apartments, setting new safety standards and assisting homeowners with conversions. However, the program was curtailed during the COVID-19 pandemic, and just over 100 homeowners have completed the assessment out of 8,000 eligible units, according to a report by City Limits.
Rebekah Morris, a senior program manager at the Pratt Center for Community Development and an advocate for the basement conversion pilot, said participants have been "grasping at straws" for more support, but gaining broader buy-in has long been a struggle. "I hate to say this would have helped, because this is a tragedy that might have been avoided if 15 years ago the city had listened and taken the issue of basement apartments seriously," Morris said. "I have some hope that this will at least spur the next government to push on this as an area of focus."
According to New York City data, at least 100,000 New Yorkers live in 50,000 or more illegal basement apartments. These residents are typically low-income and immigrant families who rely on the relatively lower rents of informal units. Based on the pilot, conversions are estimated to cost between $275,000 and $375,000 per unit.
"I could tell you that we've got some miraculous plan to solve the illegal basement problem overnight … We don't," de Blasio told the New York Times in September 2021.
With the basement pilot essentially on hold, the city has announced immediate steps to protect basement dwellers from future floods. By May 1, 2022, the city will create a database of below-ground spaces and provide enhanced communications to homeowners with basement apartments. Emergency responders will receive training for more efficient basement evacuations, and community organizers will conduct door-to-door canvassing to reach at-risk residents. The city will also work with homeowners to connect driveways to sewers to reduce flooding in residential areas.
Morris, however, argues that the status quo—illegal apartments and uncontrollable flooding—highlights how poor and minority New Yorkers are most at risk from a variety of crises. "It just acknowledges that the people who have the least impact on our climate are the ones who are suffering the most and are hit most by the affordable housing crisis," she said. "Ida showed how brutal that intersection is. And I hate to say it, but I expect this will continue."
ADUs Offer an Affordability Solution
After the 2008 foreclosure crisis, Diane Limas began canvassing homeowners in Chicago's minority-dominated Albany Park neighborhood as part of the Albany Park Neighborhood Council, whose priority was to maintain homeownership in the community. Limas and her group soon identified another at-risk population: dozens of families living in illegal basement units that could easily end up homeless if the house above them were foreclosed on. Limas recalls looking at the ad-hoc apartments, with low pipes and tiny windows, and questioning whether they were truly safe places to live.
"The response would be 'if we weren't living here, at the affordable rent we have here, my family and I would be on the street,'" Limas said. By and large, she said, people were paying between $400 and $600 a month for the units, significantly lower than above-ground apartments.
Legalizing those apartments, the group realized, could dramatically increase the city's housing stock while giving small landlords another income source to stay afloat. The council—now renamed Communities United—has worked with the city of Chicago on an effort to increase accessory dwelling units (ADUs), independent living quarters with full kitchens and bathrooms. Besides basements, ADUs include granny flats, coach houses, and casitas.
An Urban Land Institute report found that 2-4 flats—residential buildings with up to four apartments, usually stacked—account for nearly 30% of total residential units in Chicago, many of which include a basement or garden unit. While renting that space was common, the report found that those buildings are increasingly being removed, exacerbating affordability issues. The ADU initiative offers assistance to landlords to rehab basement units and make ADUs a viable income source.
While the solution may seem straightforward, many zoning codes limit ADU access. For example, limits on the number of residents in a single building, mandated parking spots, and a lack of financing tools make legalization difficult.
That is beginning to change. Lawmakers in Utah passed a bill in spring 2021 that would allow most homeowners to rent out basement apartments in single-family homes as part of an effort to address the state's housing shortage. California has enacted several policies designed to make ADUs easier to build, leading to a significant increase in housing availability. A University of California, Berkeley report found that ADU permits in the state increased from 6,000 to almost 16,000 between 2018 and 2019, and the number of completed units more than tripled from 2,000 to almost 7,000 in the same period. A separate University of California, Los Angeles study estimated that ADU legislation had created the potential for nearly 1.5 million new housing units.
But ensuring those new units are safe can require its own limitations. Boston, for example, launched an ADU program in 2017, offering zero-interest loans for eligible property owners to convert basements to living spaces. However, the city's code places restrictions on basement units for homes located in a FEMA flood zone. In October 2021, Acting Mayor Kim Janey signed a zoning overlay that restricts development in areas that could be flooded in a storm event with 40 inches of sea level rise, also known as a 1% chance storm event. That will further limit underground living spaces in those areas, requiring that any space under the sea level elevation standard be used only for flood prevention, storage, or parking.
"For Boston to grow and thrive for generations to come, we must ensure that buildings constructed today are resilient and protected from the impacts of climate change," said Boston Planning and Development Agency Director Brian Golden in a statement. "By updating our zoning code to go above and beyond the FEMA flood maps, Boston is leading the way in not only preparing for the storms of today, but the storms of tomorrow."
Mitigating Risk
The flooding after Ida may only be a preview of the future. Studies have found that coastal cities face significant flooding risk as sea levels rise and storms grow more intense. That reality poses risks to homeowners—even those who live outside traditional flood zones, who may not know their risk until it's too late.
Efforts are now underway to protect homeowners when damage occurs, offer low-income residents more money to make repairs, and provide homebuyers much-needed safety information from the outset.
In 2017, Sam Brody, director of the Center for Texas Beaches and Shores at Texas A&M University at Galveston, launched Buyers Be-Where, a website that compiles advanced flood and pollution data to develop a risk score for houses in several cities, including Houston, New Orleans, Seattle, and Miami. The idea, he said, was to give people environmental data on their homes similar to the school and crime data many homeowners consider, helping buyers make informed decisions.
"We try to be explicit that this is not meant to dissuade someone from buying a home," Brody said. "What I tell people is if my wife likes a house because it has an amazing kitchen, but I learn that it's in a flood zone, at least I know what I'm getting into."
Under a contract with the state of Texas, Brody's team will expand the website with new models and information about mitigation, including a tool that will help homeowners calculate how much certain mitigation investments will lower their flood damage risk.
But even homeowners equipped with knowledge face steep bills to prepare homes and basements for flooding and to clean up after a storm. Ida caused between $16 billion and $24 billion in property damage in the Northeast, according to property information firm CoreLogic.
That's why a new collaboration between the University of Pennsylvania's Wharton Risk Management and Decision Processes Center, the non-profit Center for New York City Neighborhoods (CNYCN), and the New York City Mayor's Office of Climate Resiliency aims to get flood insurance into the hands of low- and moderate-income families. The pilot program is exploring an "inclusive insurance" model, using a parametric flood insurance policy that triggers automatic payouts to policyholders in a community after a certain severity of storm.
The idea, said CNYCN Vice President of Development and External Affairs Jessica Wells-Hasan, is to get money to homeowners quickly after a disaster, with no receipts and no weeks-long documentation process. "This is money that people can use in whatever manner they want, to do whatever repairs or preparations are needed," Wells-Hasan explained.
CNYCN is also expanding research on the community benefits of insurance and educating homeowners, helping them right-size flood coverage and better articulate their risk. That, Wells-Hasan said, will help at-risk homeowners be more prepared and ensure there are fewer barriers to safety for basement dwellers.
"We want everyone who is renting a basement or who owns a home with a basement to have flood insurance, no matter what other amazing insurance policies they have," she said. "Let's get rid of the red tape so we can all become more aware and get these apartments out of their illegal and unrecognized status."